Mortgage Renewal in Ontario: When Should You Start Shopping for a Rate?
The question: this came up in a r/PersonalFinanceCanada thread from an Ontario homeowner renewing for the first time. I have answered it for York Region buyers and renters, with sources below.
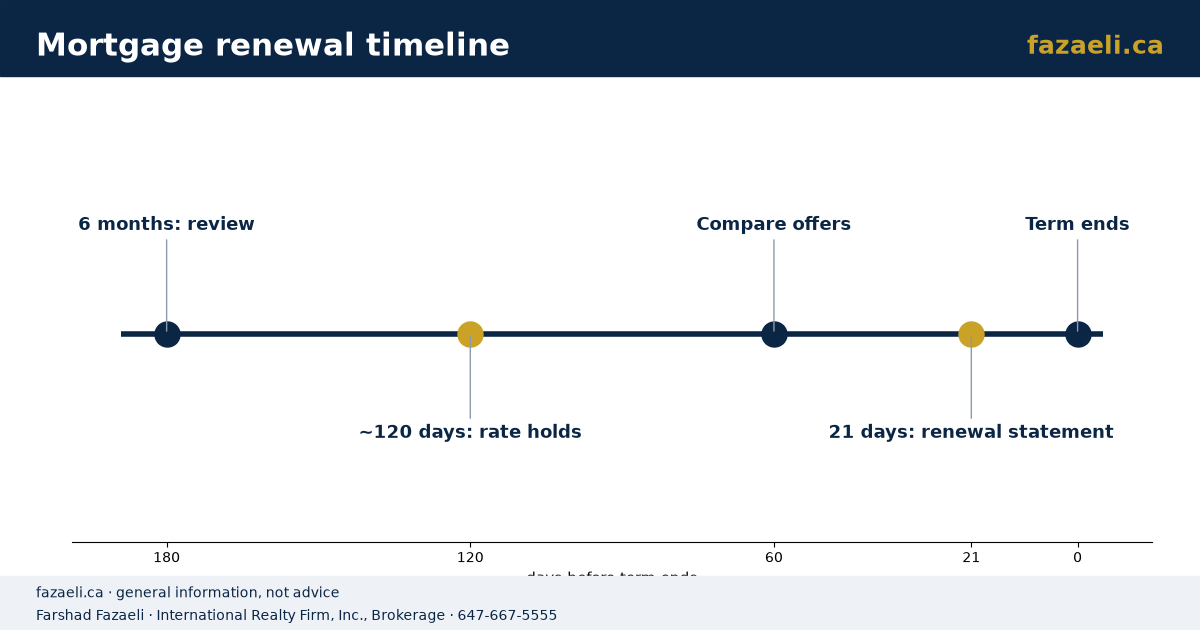
Short answer: start comparing offers about four to six months before your term ends, and do not simply sign the first renewal letter your lender sends. Many lenders will hold a rate for around 120 days, so you can lock in a quote and still take a lower one if rates fall before you sign.
What the rules require from your lender
If your mortgage is with a federally regulated lender such as a bank, it must send you a renewal statement at least 21 days before your term ends, and must also tell you at least 21 days ahead if it will not renew (FCAC, Renewing your mortgage). The Financial Consumer Agency of Canada (FCAC) advises starting to shop a few months earlier and not waiting for that letter, because if you do nothing the renewal may be automatic.
A practical timeline
- Six months out: check your balance, payment and any prepayment room. Note your renewal date.
- About four months out: ask your current lender, at least one other lender and a mortgage broker for written quotes. Ask whether each can hold the rate and for how long.
- One to two months out: compare offers on total cost, not only the rate: term length, prepayment privileges, penalties and fees.
- Before the statement deadline: negotiate. FCAC notes you can show competing offers to your current lender to ask for a better rate.
What switching lenders can cost
Moving at renewal is usually penalty-free, but FCAC lists possible costs: discharge, registration, transfer or assignment fees, an appraisal, and other administration fees. Ask the new lender which of these it covers.
There is also a qualification point. OSFI's minimum qualifying rate for uninsured mortgages is the greater of 5.25% or your contract rate plus 2% (OSFI). OSFI has said straight switches of uninsured mortgages at renewal no longer need to be re-tested; confirm with the new lender how your file will be treated.
Common mistakes
- Signing the renewal letter without asking for a better rate.
- Comparing only the posted rate and ignoring penalties if you might sell before the term ends.
- Starting so late that there is no time for a new lender's appraisal and paperwork.
Need a hand with this?
Call or text me at 647-667-5555. I work across Richmond Hill, Markham, Vaughan and the rest of York Region, in English and Persian (فارسی).
Related reading
- Interest rates and timing in GTA real estate
- Understanding closing costs for Ontario homebuyers
- Long-term residential property investment in the GTA
Sources
- Financial Consumer Agency of Canada, Renewing your mortgage
- OSFI, Minimum qualifying rate for uninsured mortgages
All sources accessed October 2026.
Farshad Fazaeli, International Realty Firm, Inc., Brokerage. Unit 104, 391 Major Mackenzie Dr E, Richmond Hill, ON L4C 1H8. Phone 647-667-5555. This article is general information, not legal, tax or mortgage advice. Market figures are board-wide summaries and are not an appraisal of any property. Not intended to solicit buyers or sellers already under contract with a brokerage.
FAQ
How early can I renew my mortgage in Ontario?
Many lenders let you lock a renewal rate about 120 days before your term ends. Renewing earlier than that can trigger a prepayment penalty, so ask your lender.
When must my bank send a renewal statement?
Federally regulated lenders must send the renewal statement at least 21 days before the end of the term, according to FCAC.
Does switching lenders at renewal cost money?
It can. FCAC lists discharge, registration, transfer, appraisal and administration fees. Some lenders cover these to win the business.
Richmond Hill & GTA · International Realty Firm, Inc., Brokerage
647-667-5555 · info@melk.ca